Roof insurance claims in Broken Arrow, done by the book
We document, we meet the adjuster, we build to the approved scope and we supplement what was missed. You file and control your claim, you pay your deductible, and nobody's estimate gets thrown out over a paperwork trick.
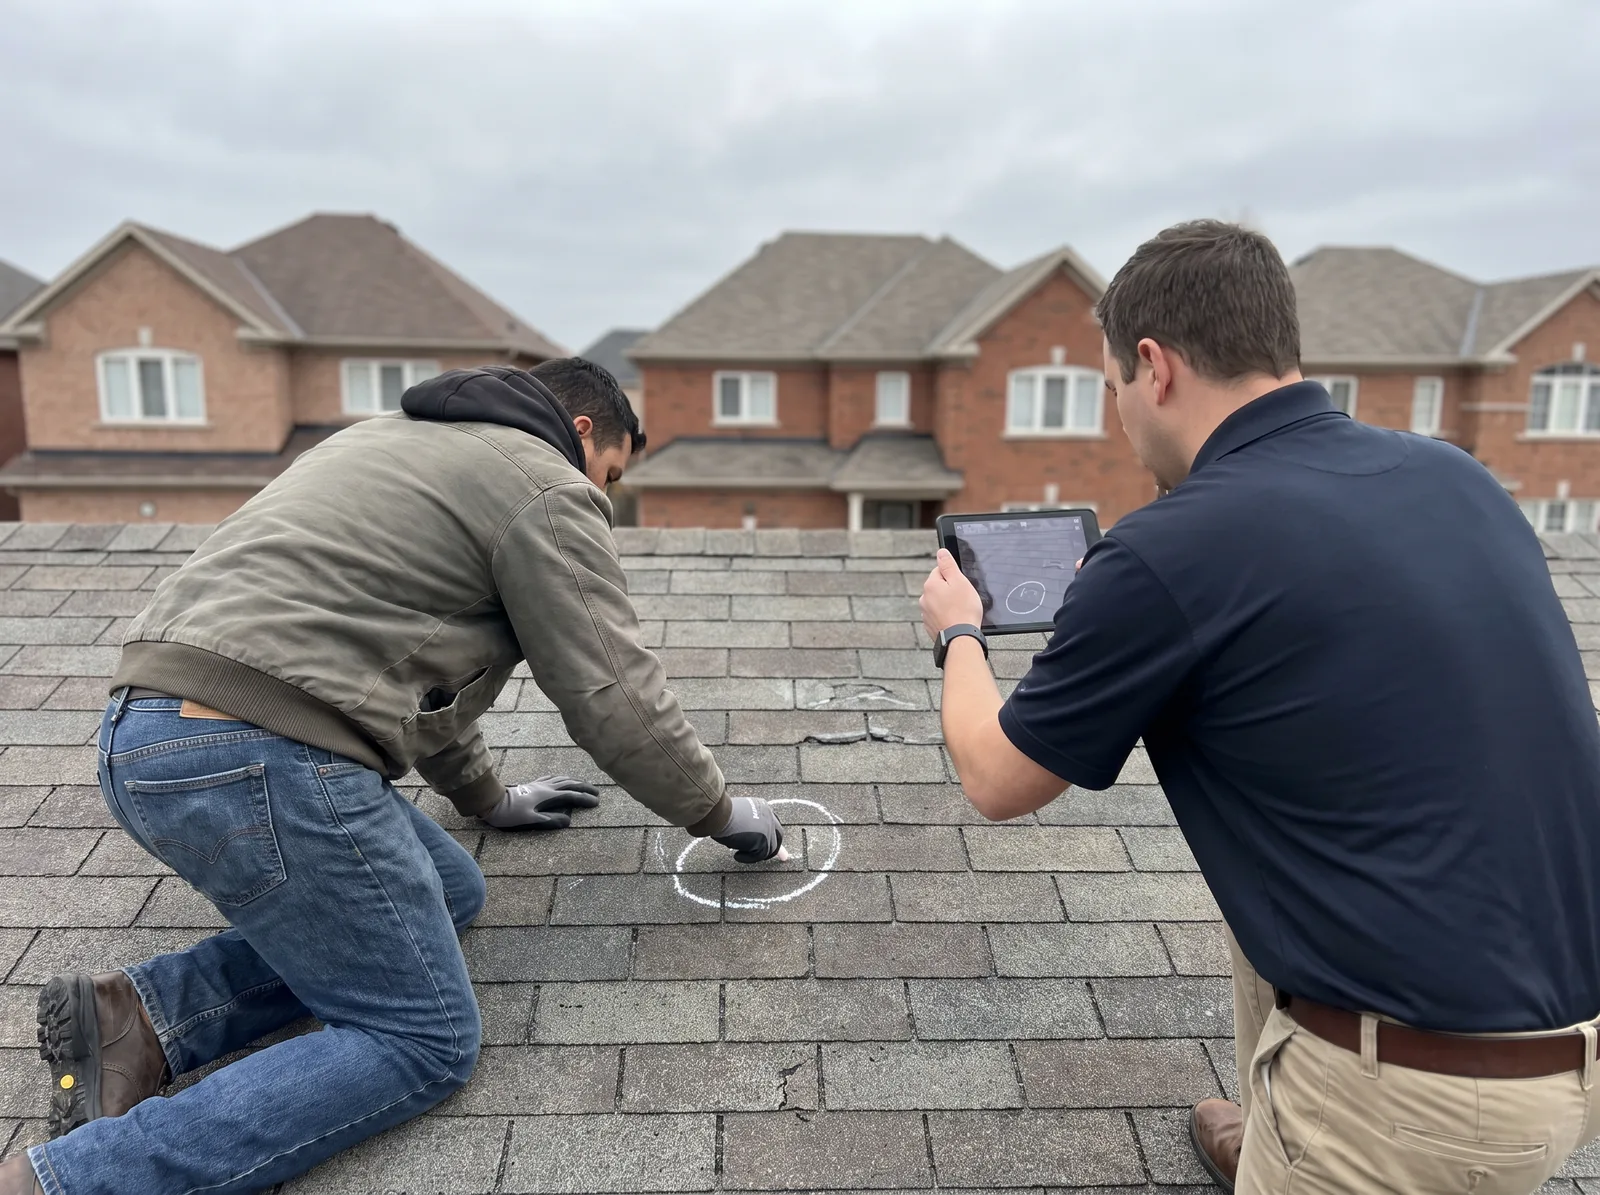
After every big Green Country storm, two things happen: the adjusters get overwhelmed, and the storm chasers arrive. In that environment the roofer's job on a claim is narrow and specific — document the damage so well that an adjuster with fifteen minutes and forty roofs to see can't miss it, meet them on the roof, build the estimate in the same line-item format the carrier uses, and supplement politely for whatever was left off: the ice-and-water, the drip edge, the code-required ventilation, the second layer nobody knew was there. We do that. We don't file the claim for you, we don't take an assignment of your benefits, and we don't 'handle' your deductible.
That last part is the law. Under 59 O.S. §1151.30 a roofing contractor in Oklahoma may not advertise or promise to pay, waive or rebate any part of your deductible — nor offer to 'compensate' you for some service as a workaround — and if one does, your insurer is entitled to ignore that roofer's estimate entirely. Every estimate we write includes the written notice of that rule the statute requires. Pay the deductible, get the receipt, and your recoverable depreciation gets released without an argument.
What's changed lately is the policies themselves. Since the 2023 and 2024 storm years, Oklahoma carriers have been moving roofs to actual-cash-value settlement, adding percentage wind-and-hail deductibles (one or two percent of dwelling coverage — $4,000 to $8,000 on a $400,000 house), shortening the window to report a storm claim, and inspecting roofs at renewal. All of which means a claim is worth more if it's documented well and filed promptly, and worth less if you wait. If your roof was on the house for the May 2024 hail or the March 2026 storms, read your declarations page and call us for the inspection now, not next spring.
What's included
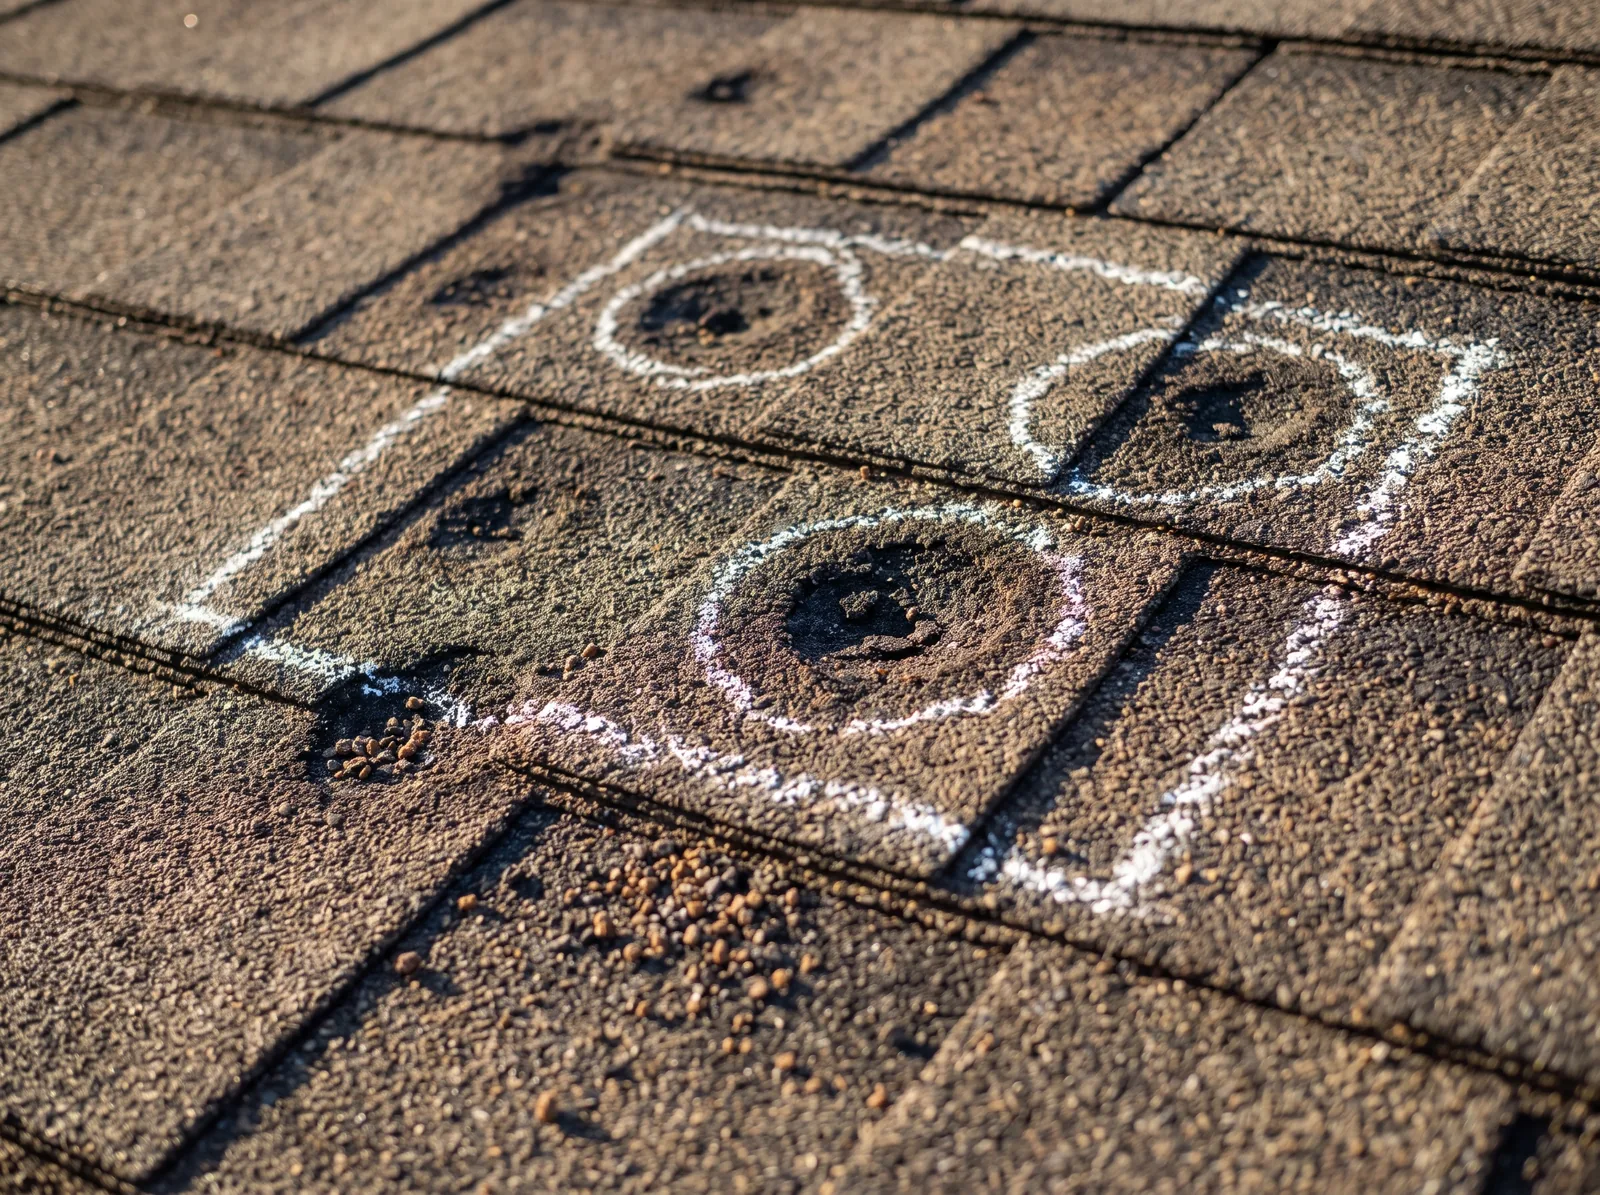
- Damage documentationChalk-marked test squares, per-slope hit counts, soft-metal photos, a roof diagram and a written report.
- Adjuster meetingWe meet your adjuster on the roof with the marks still there and walk every slope together.
- Estimate to scopeLine-item estimate in the carrier's format, matched to the approved scope, with code items called out.
- SupplementsMissed items — ice-and-water, drip edge, ventilation, decking, a second layer — documented and submitted.
- Deductible complianceWritten §1151.30 notice with every estimate; deductible paid by you, receipted, depreciation released cleanly.
- Completion paperworkCertificate of completion, final invoice and photos for the recoverable-depreciation release.
What a roof claim costs you in Broken Arrow, OK
| Job | Typical price | Notes |
|---|---|---|
| Inspection & written damage report | Free | Yours whether you file or not |
| Adjuster meeting | Included | When we do the work |
| Estimate in carrier format + supplements | Included | Xactimate-style line items |
| Your cost on an approved claim | Deductible only | Plus any upgrade you choose |
| Class 4 upgrade on a claim roof | +$2,000 – $4,000 | Some carriers pay part of it |
| Code-required items (ice-and-water, drip edge, ventilation) | Supplemented | Covered when the policy has ordinance coverage |
| Public adjuster or attorney referral | On request | For denied or underpaid claims |
On an approved claim you pay your deductible and any upgrade you choose. Estimates are itemized in the carrier's format and include the written deductible notice required by 59 O.S. §1151.30.
Recent work
Questions we get about roof insurance claims
Should I file a claim for hail damage?
Only if the damage is real and the payout clears your deductible by enough to matter. We'll tell you the hit counts and what a replacement is worth on your policy before you decide. Filing a claim that's denied still shows on your history.
What's the difference between ACV and RCV on a roof?
Replacement cost value pays what a new roof costs (minus the deductible), with the depreciation released when the job's done. Actual cash value pays what your old roof was worth — a 15-year-old shingle roof might be valued at 30 percent of new. Many Oklahoma policies moved roofs to ACV or a roof schedule at renewal in 2024 and 2025; check your declarations page.
Can you 'work with my deductible'?
No, and be suspicious of anyone who says they can. Oklahoma law prohibits paying, waiving or rebating deductibles or compensating you for a 'service' to get around it, and lets the insurer disregard that roofer's estimate. You pay the deductible; we give you the receipt.
What is a contingency agreement?
A contract that says if the claim is approved, you must use that roofer at whatever price the insurer pays. Storm chasers use them to lock up roofs the morning after a storm. You don't need one to get an inspection or a tarp from us, and we don't ask for one.
My claim was denied. Now what?
Ask for the denial in writing and the adjuster's photos. If our documentation shows damage the adjuster missed, we request a re-inspection with our report attached. If it's still denied and the damage is clear, a licensed public adjuster or an attorney is the next step, and we'll refer you to one.
Does the carrier have to pay for code upgrades?
If your policy has ordinance-or-law coverage (most do, at 10 percent of dwelling coverage), items the current code requires — ice-and-water barrier, drip edge, proper ventilation — are covered when they're in the approved scope. We document and supplement for them.